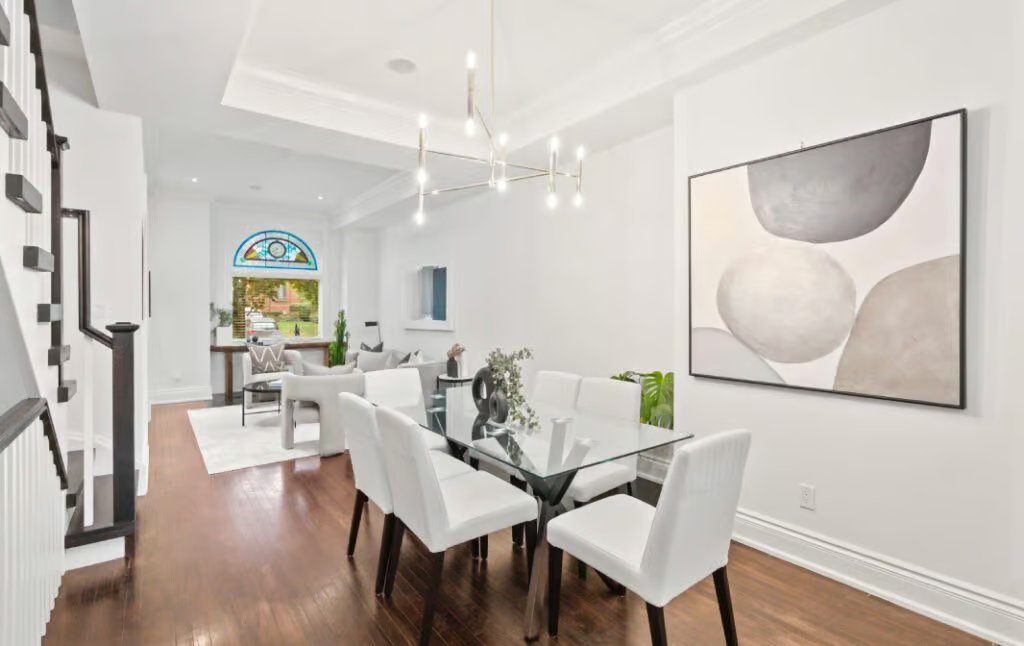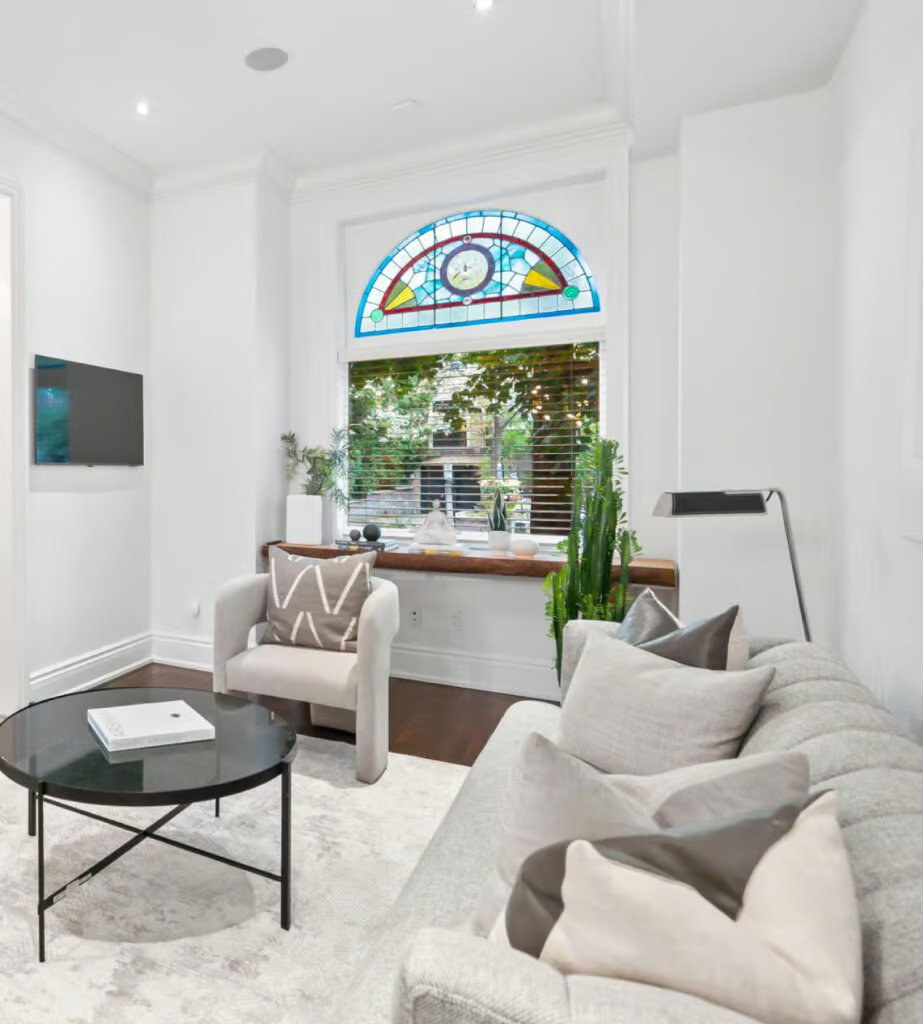
Buying your first home isn’t like any other real estate purchase. Although most of the steps are similar, every aspect of the experience is intensified somehow.
This milestone is more exciting, more intimidating, and can be more confusing when you have never bought a house before. Everyone you know is also there to provide their opinions on how you should proceed.
Some of the tips you hear are good; others might make sense, except the market has changed and many long-held guidelines no longer apply.
What can you do to ensure the best outcome possible? Start by avoiding some of the worst mistakes when buying a house for the first time.
Want the latest facts when it comes to Midtown Toronto Real Estate? Subscribe to our newsletter for up-to-date statistics, tips, and early access to our listings.
Not Accounting for Market Changes
The fact that real estate conditions change goes without saying, especially in a city like Toronto where demographics evolve day by day. One moment, the population is increasing as people move here for the excitement and opportunities. Homes become more in demand, competition increases, and real estate prices rise.
The next thing we know, there’s an exodus from the city as people move away for a quieter lifestyle. When that happens, houses take longer to sell and prices can fall. Ideally, these are the best times to start looking for a house, but the situation is always nuanced.
What are some of the other things to know before buying a house in Toronto for the first time? Get more details in the posts below:
- Who Qualifies as a First-Time Home Buyer
- When Should You Buy Your First House?
- Our Top Real Estate Terms for First-Time Home Buyers
Assuming the Market Is (Or Isn’t) On Your Side.
“Now is a terrible time to buy a house. It’s a seller’s market!” This might be one of the first things you hear when you casually mention that you’re thinking about a house of your own.
If you’re currently renting and have the cash resources and borrowing power, waiting can be terrible advice even if prices aren’t at their lowest point. Every month that goes by is another rent payment that could have helped you build equity.
Another variation of this well-intended but no-less-questionable advice is “It’s a buyer’s market! Now is the time, go, go, go!” At first glance, conditions may seem to be in your favour, but what if you’re not ready?
If you buy a home without a sufficient financial cushion, you may find yourself “house poor.” While homeownership comes with a sense of accomplishment, it’s stressful wondering how you’re going to cover your mortgage in addition to all other expenses.
Another scenario is where you buy before you’re ready, and the house doesn’t suit your long-term goals. Now, you find yourself facing another expensive move, which can quickly negate any financial advantages.
Every Market Has Challenges and Opportunities
We have said it before, and we will continue to shout from the rooftops that the best time to buy your first house is when you’re ready. No matter what, there will be opportunities and obstacles.
- Some buyers are surprised when the house they want goes into multiple offers. However, it can happen even in a favourable market.
- Some housing structures and locations will always be in high demand regardless of what is happening everywhere else.
If the bidding gets to be too much, you can pivot your strategy and look for an alternative. For example, imagine everyone else is competing over a single-family detached home in a hot neighbourhood. You could turn your attention to a condo or an area that flies under the radar.
To further assess your readiness, ability, or what advantages you have in today’s market, talk to a local real estate agent who knows the community.
Searching for houses for sale in Midtown Toronto? Start by checking out our featured listings.
Being Under or Over Specific About the Home You Want
Of all mistakes by first-time buyers, unrealistic expectations are the most prevalent. Some people will not consider a listing unless it’s in a certain neighbourhood, in absolutely meticulous condition, is a particular age, or meets a host of other almost impossible criteria.
Even with an unlimited budget, some concessions are necessary. When you’re trying to get a foothold on the property ladder, you’ll typically need to be a little more flexible. That’s not to say you can’t have some stipulations.
A move-in-ready house might be non-negotiable if you don’t have the time or budget for a remodel. You just may need to be flexible about what constitutes “move-in ready.”
Functional bathrooms and a roof that doesn’t leak deserve a place on your list of must-haves. Stainless steel appliances or a butler’s pantry might need to go on the back burner for now. What’s important is that you get into the market with a home that makes you happy and appreciates in value over time.
Being too general can also work against you. If you don’t know what you’re looking for, how will you recognize it when you find it? Successful first-time home buyers have a healthy balance between what they need and what would be nice to have. Even more importantly, they have a well-thought-out strategy on how to achieve it.
Forgetting About the Pre-Approval
A mortgage pre-approval means filling out an application for an official estimate of how much you can borrow. Sellers prefer offers from buyers who can prove access to financing, which is where a Certificate of Pre-Approval comes in.
In the past, many real estate agents would position this step as optional, but highly beneficial. In this fast-changing and challenging market, a pre-approval is all but non-negotiable, especially when buying a house for the first time.
Are you still wondering what city or what neighbourhood might be right for you? Here are some fun posts to help you narrow it down:
- Wychwood Vs The Annex: Where to Buy Your New Home
- Toronto Versus Ottawa: The Best Place to Live in Ontario
- Midtown Toronto Versus Mississauga: The Best of the Best
Not Taking Advantage of Every Available Resource
Running the numbers on your ideal home can feel discouraging at times. In addition to the listing price, there are closing costs, which include legal fees, mortgage insurance (if applicable) and land transfer taxes.
While it’s important to be prepared for all costs and maintain a healthy cushion, you should also make use of every federal, provincial, and municipal incentive available at the time of your purchase. Some of the well-known programs include:
Land transfer tax rebates: Land transfer taxes are among your most expensive closing costs. Fortunately, first-time buyer rebates are also significant, both from the province and the City of Toronto.
First Home Savings Account (FHSA): If you haven’t yet signed up for an FHSA, we encourage everyone who qualifies to do so as soon as you can. What other investment vehicle allows you to save on taxes on both deposits and qualifying withdrawals?
Home Buyer’s Plan: You can take savings you already have and apply them to your purchase. Then, you have 15 years to repay those funds into your account to maintain their tax-free benefit.
There are also tax credits for first-time home buyers and HST rebates when purchasing newly constructed or substantially renovated homes. When you’re ready to buy, be sure to ask your agent if there are any initiatives you should know about. From there, you can build a strategy that gets you a fantastic home in a great neighbourhood and at the best possible value.
Are you ready to explore the possibilities of homeownership? Our Midtown Toronto real estate agents are here for you. Reach out to us at david@batorigroup.com, bobby@batorigroup.com or call (416)-485-7575 with any questions.
Book a Consultation
Whether buying or selling, our team can help you achieve your real estate goals. Start the conversation today.